How to Create an Estate Plan That Works
It can be easy to overlook. However, an estate plan is essential for nearly everyone, whether you have a lot of money or just a little.
It can be easy to overlook. However, an estate plan is essential for nearly everyone, whether you have a lot of money or just a little.
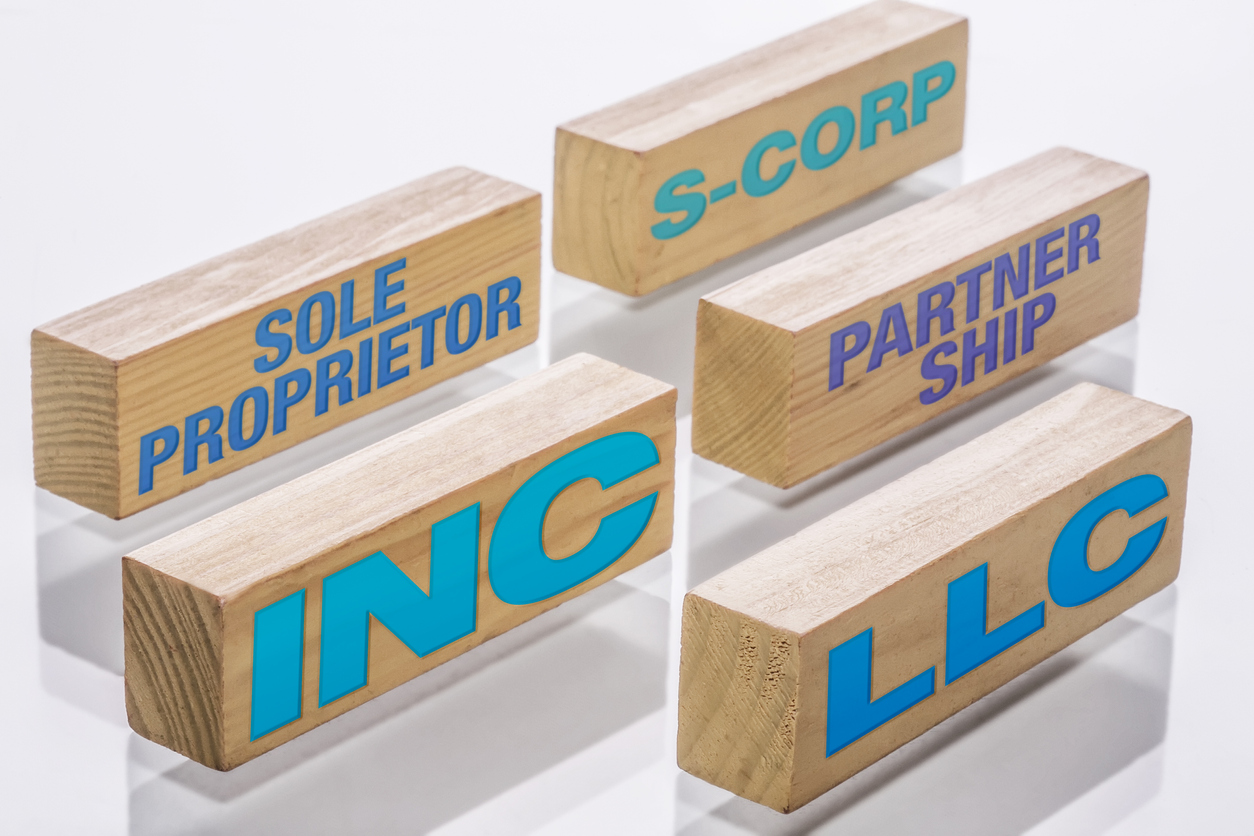
At Sims & Campbell, our experienced estate planning attorneys are committed to providing our clients with the latest updates on legal developments that could impact them. To ensure you have the most accurate and timely information, we will now be posting all news regarding the Corporate Transparency Act (CTA) right here on our blog. On March 2, 2025, the U.S. Treasury Department announced a suspension of the March 21, 2025, deadline for filing under the Corporate Transparency Act (CTA) for both domestic companies and U.S. citizens. Additionally, the Treasury announced it will not enforce any penalties or fines. This decision follows a series of legal and regulatory developments regarding the CTA and its enforcement. For more details, see below: The Corporate Transparency Act (CTA) is a U.S. law that was enacted as part of the National Defense Authorization Act for Fiscal Year 2021. The purpose of the CTA is to enhance transparency in the ownership of companies and to combat illicit activities like money laundering, tax evasion, and terrorist financing by making it harder for criminals to hide behind anonymous shell companies. The CTA requires certain businesses, including corporations, limited liability companies (LLCs), and similar entities, to disclose information about their beneficial owners. A beneficial owner is an individual who, directly or indirectly, owns or controls at least 25% of a company or who exercises substantial control over it. The CTA has far-reaching implications for both domestic and foreign companies, and understanding its requirements is essential for compliance. With that in mind, we’ll keep you up to date on any changes, deadlines, and new regulations that emerge. Read on for the latest news on the Corporate Transparency Act. Here are the key takeaways: Suspension of the Filing Deadline: The Treasury has suspended the filing requirement under the CTA for domestic companies and U.S. citizens. The March 21, 2025, deadline is no longer applicable at this time. No Penalties or Fines At This Time: The Treasury Department announced it will not enforce any penalties or fines associated with the BOI reporting rule under the existing regulatory deadlines. Proposed Rulemaking to Narrow Scope: The Treasury is preparing a proposed rulemaking that could narrow the scope of the CTA’s reporting requirements to focus exclusively on foreign reporting companies. These are entities formed under foreign law but that have registered to do business in the U.S. by filing a document with a secretary of state or similar office. Legal Uncertainty: The proposed narrowing of the rule is inconsistent with the original text of the CTA and could be subject to legal challenges. While it is unclear who might challenge these changes, the possibility of legal action remains. Ongoing Legal Challenges: The CTA, which was passed during the first Trump Administration and implemented under the Biden Administration, has faced numerous legal challenges across the country. These challenges are still ongoing, with many cases pending before appellate courts. Impact on Information Already Filed: The Treasury has not clarified what will happen to the information already submitted…
Divorce significantly impacts estate planning, requiring updates to wills, trusts and beneficiary designations to ensure that assets are distributed according to new intentions.
Choosing the right storage location for your will ensures that it remains secure, accessible, and legally valid when needed.
We previously shared updates regarding the Corporate Transparency Act (“CTA”), most recently reporting that the injunction against enforcement of the CTA was overturned and deadlines for most filers were extended to January 13, 2024. We have yet another change to report. Late December 26, 2024, a panel for the Fifth Circuit Court of Appeals reinstated the injunction until it can hear oral arguments from the parties and issue a ruling on the government’s appeal of the original injunction. We anticipate a ruling and more updates in early January. In the meantime, we continue recommend all parties required to file under the CTA should be prepared to file on short notice after the court’s ruling provides more clarity. We will continue to monitor the situation and share updates as they become available. Sims & Campbell, LLC- Annapolis and Towson Estate Planning Attorneys
This afternoon (December 23, 2024), the United States Court of Appeals for the Fifth Circuit reinstated the enforceability of the Corporate Transparency Act (CTA) effective immediately. In Texas Top Cop Shop, Inc. v. Garland, a three-judge panel of the Fifth Circuit stayed a lower court’s nationwide preliminary injunction against the CTA, which was issued on December 3, 2024. This means that, among other obligations, the January 1, 2025, compliance deadline for reporting companies in existence as of January 1, 2024, is back in effect. This situation is likely to rapidly evolve. It is entirely likely that in the coming days, the challengers in this case will seek further review from the Fifth Circuit or seek relief from the United States Supreme Court. Additionally, several other federal courts are actively considering challenges against the CTA. At the time of this writing the United States Department of the Treasury’s Financial Crimes Enforcement Network (FinCEN) has not publicly released any guidance based on today’s ruling. We will continue to monitor this development closely and provide updates as they become available. For clients concerned about the implications of this ruling on their business or estate planning, please feel free to contact us. Sims & Campbell, LLC- Annapolis and Towson Estate Planning Attorneys
A recent ruling by the U.S. District Court for the Eastern District of Texas has preliminarily blocked the nationwide enforcement of the Corporate Transparency Act (CTA). This decision impacts businesses nationwide, as the CTA aimed to require U.S. business entities to report stakeholder information to the Treasury Department to combat money laundering and other illicit activities through shell companies. The injunction was issued in response to a lawsuit by Texas Top Cop Shop Inc. and co-plaintiffs, arguing that the CTA oversteps Congress's constitutional authority to regulate commerce, especially since it applies to entities regardless of their engagement in commercial activities. This ruling halts the implementation of these reporting requirements temporarily, pending further legal proceedings, which could have significant implications for estate planning and business privacy. As a result, individuals are no longer required to file but that may change in the future based on court decisions and agency regulations.We will continue to monitor this development closely and provide updates as they become available. For clients concerned about the implications of this ruling on their business or estate planning, please feel free to contact us. [For further reading on the CTA and its implications, see the article here: https://news.bloombergtax.com/daily-tax-report/corporate-transparency-act-blocked-nationwide-by-texas-court ] Sims & Campbell, LLC- Annapolis and Towson Estate Planning Attorneys
Effective January 1, 2024, the Corporate Transparency Act (the “CTA”) will implement beneficial ownership information reporting requirements for corporations, limited liability companies and other business entities that were created in or are registered to do business in the United States. The CTA requires that certain information about the business’ owners be provided to the Department of the Treasury’s Financial Crimes Enforcement Network (“FinCEN”) and imposes significant penalties for noncompliance. The purpose of the CTA, which is part of a broader effort by FinCEN to try to crackdown on illegal activity such as money laundering, corruption, tax fraud and terrorist financing, is to provide greater transparency of owner information to try to prevent criminals from hiding illegal property in the United States. Who is required to file? Corporations, limited liability companies and other business entities that were created by a filing with a secretary of state or a similar office to create the entity or, for foreign companies, a registration to do business in the United States. The CTA contains 23 exemptions, mostly for large companies, such as publicly traded corporations, and businesses that the federal government heavily regulates, as these companies are already providing the information to the government. Limited liability companies created for estate planning purposes must comply with the CTA. What to file? A business that is required to report beneficial ownership information under the CTA (called a “reporting company”) will be required to provide: legal name and any trade name or dba; address; jurisdiction in which it was formed or first registered, depending on whether it’s a U.S. or foreign company; and taxpayer identification number. For each reporting company’s beneficial owners and each reporting company applicant, the following information with respect to individual owners will also be required: legal name; birthdate; address (in most cases, a home address); and an identifying number from a driver’s license, passport or other approved document for each individual, as well as an image of the document that the number is from. There can be up to two individuals who qualify as a reporting company’s applicants: the individual who directly files the document that creates, or first registers, the reporting company; and the individual that is primarily responsible for directing or controlling the filing of the relevant document. A reporting company is only required to report company applicants if it is created or registered on or after January 1, 2024. When to file? A reporting company created or registered before January 1, 2024 is required to file before January 1, 2025. A reporting company created or registered on or after January 1, 2024 is required to file within 30 calendar days of receiving actual or public notice that the company has been created, or upon receipt from your state’s secretary of state or similar office that the company was created or registered, whichever is earlier. FinCEN has reported that it will accept reports electronically beginning January 1, 2024. There is a proposal to extend the time to file for the first year…
Estate planning for digital assets is an increasingly important aspect of overall estate planning due to the growth of online accounts, cryptocurrencies, and other digital assets. It involves organizing and planning for the management and distribution of your digital assets in the event of your incapacity or passing. Here are key considerations and steps to effectively include digital assets in your estate plan: Take Inventory of Digital Assets: Start by creating a comprehensive list of your digital assets, including: Financial Accounts: Online banking, investment accounts, PayPal, etc. Social Media and Email Accounts: Facebook, Twitter, Gmail, etc. Digital Media: Music, videos, ebooks, etc. Cryptocurrencies: Bitcoin, Ethereum, etc. Domain Names and Websites: If you own any. Online Storage Accounts: Dropbox, Google Drive, etc. Organize Documentation and Access Information: Document account information, login credentials, and any two-factor authentication codes. Store this information securely, either in a physical location (like a safe deposit box) or a password manager. Ensure a trusted individual knows how to access this information. Appoint a Digital Executor: Designate a trusted person as your digital executor in your will or estate plan. Grant them the authority to access, manage, and distribute your digital assets in accordance with your wishes. Review Terms of Service Agreements: Understand the terms of service for each digital platform or service you use, as they may have specific rules about transferring or accessing accounts after death. Comply with any necessary procedures for handling digital assets outlined in these agreements. Communicate Your Wishes: Clearly communicate your wishes regarding digital assets to your loved ones, digital executor, and any other relevant parties. Provide guidance on how you want each type of digital asset handled, shared, or preserved. Regularly Update Your Plan: Regularly review and update your estate plan, especially if you acquire new digital assets or change online account information. Consult with Professionals: Seek advice from estate planning attorneys or financial advisors who are knowledgeable about digital asset planning to ensure your plan is thorough and legally sound. Consider Legal Assistance: Depending on the complexity of your digital assets and your overall estate, consult a lawyer specializing in estate planning and digital asset management to ensure your plan is comprehensive and legally binding. By integrating your digital assets into your estate plan, you can help ensure a smooth transition of your online presence and assets to your chosen beneficiaries and loved ones. Contact us to schedule a complimentary call with one of our experienced estate planning attorneys! Sims & Campbell, LLC- Annapolis and Towson Estate Planning Attorneys
As empty nesters approach retirement age, they often start considering moving closer to their adult children to maintain closer family ties. However, as with any move, there are a lot of factors to consider, from choosing the right neighborhood to budgeting for expenses. Here, Sims & Campbell Estates and Trusts outline some of the most important steps empty nesters should take when they're looking to move closer to their kids.Consult Your ChildrenThe first step in moving closer to your adult children is to consult with them about their ideas and preferences for the move. It's important to have an open and honest conversation with your children about your expectations and your reasons for relocating. You might have one idea about what your move should look like, but your children may have different expectations or ideas. By discussing your plans with your children, you can create a plan that everyone is happy with and that works for everyone's needs.Explore Potential NeighborhoodsTo find your perfect home, you need to explore potential neighborhoods and areas. This helps you understand the local environment, check out nearby amenities, and get a feel for the area. Visiting these locations can guide you in making an informed decision about which place suits you best.Get the Scoop from Local ResidentsWhen visiting potential neighborhoods, make sure you talk to local neighbors about the area. This will give you an idea of what it's really like to live there, and what the community is like. You can ask about things like noise levels, crime rates, and the overall vibe of the community.Consider Healthcare, Dining, and Transportation OptionsAnother important consideration when relocating is the availability of healthcare, dining, and transportation. Make sure you spend time researching so you can find the best options for your needs. Healthcare is particularly important for older adults, so make sure you research local healthcare providers in the area, including doctors, dentists, and hospitals.Navigate Zoning LawsBefore relocating, it's important to research any laws or regulations that could affect your lifestyle choices. For example, some areas have strict noise ordinances or rules regarding how many pets you can have. Make sure you understand these regulations before you make your move, so you can avoid any unpleasant surprises down the road.Plan a Budget for Moving-Related CostsRelocating can be expensive, so make sure you budget for all relocation expenses, including the costs of hiring a moving company, renting a truck, and paying for any storage units. Other expenses to factor in can include closing costs and real estate agent fees. Make sure you have a solid budget in place before you start the moving process.Decide Whether to Sell or Close Your BusinessIf you are a small business owner, you’ll need to decide what to do with it when you move. There are two primary options: sell it or close it. You’ll probably want to start by getting an accurate valuation of the business first because the answer might determine your next steps. Then, depending on your business structure, you may…